
 English
 Français
 Español
 Português
 BTC
 ETH
 LTC
 BCH
 USDT
 DOGE
 DASH
 USDC
 XRP
 XMR
 TRX
 BNB
 SHIB
 SOL
 DAI
 ZEC
 ETC
 POL
 ADA
 XLM
For years, the most visible use of stablecoins was moving money between cryptocurrency exchanges. That is no longer the whole story. In 2026, payment networks, fintech companies and treasury platforms are increasingly using dollar- and euro-linked tokens behind the scenes to settle transactions, fund cards, move working capital and deliver cross-border payouts. The customer may never hold a wallet or even know that a blockchain was involved.
This shift does not mean stablecoins have replaced bank accounts, card networks or accounting software. Instead, they are becoming an additional settlement layer: a way to move a digital representation of money continuously while regulated providers handle conversion, compliance and access to local payment systems. The strongest business case is not speculation. It is reducing the time and operational friction between an approved payment and the arrival of usable funds.
The difference between a stablecoin and a stable payment
A stablecoin is a digital token designed to track a reference asset, usually the US dollar. That design can reduce the price swings associated with assets such as bitcoin, but the word “stable” is not a guarantee. Reliability depends on the issuer, the quality and availability of reserves, redemption rights, custody arrangements, the blockchain used and the legal framework in each market.
For a company, the useful outcome is not simply owning tokens. It is being able to issue an invoice, receive value, reconcile the payment and convert or reuse the balance under predictable rules. A technically fast transfer can still create operational problems if the sender chooses the wrong network, if the recipient cannot redeem the token locally or if transaction data does not match the invoice.
That is why the emerging infrastructure increasingly hides blockchain complexity. Payment providers can quote an exchange rate, screen participants, move a stablecoin between institutions and pay the recipient in local currency. In this model, the token acts as the settlement asset between service providers rather than as a new interface every finance team must learn.
Business adoption is becoming measurable
Evidence of business use is beginning to appear in payment-network data. In October 2026, Visa said that approximately 17% of stablecoin-linked card volume in its fiscal year to date came from business and commercial card programmes. The company reported more than 160 stablecoin-linked card programmes worldwide and payment volume across those programmes almost 200% higher than a year earlier. Visa also said business-to-business flows had the highest cross-border share in the payment activity it analysed.
Settlement volumes remain small beside the total scale of conventional payments, but the direction is notable. Visa reported in September that stablecoin settlement had exceeded a $20 billion annualised run rate, more than fifteen times the level recorded a year earlier. Earlier in 2026, the network had expanded its pilot to nine blockchains. These figures describe Visa’s own ecosystem, not the entire market, yet they show that stablecoin infrastructure is moving beyond isolated demonstrations.
Merchant acceptance is also broadening. The Cryptwerk USDC directory listed more than 1,600 companies accepting USDC in October 2026, spanning internet services, business services, shops and payment tools. A directory listing is not proof that every checkout option is currently available, so companies should still confirm the supported token, network, fees and refund terms directly with the merchant.
Why cross-border payments are the natural first use case
Domestic bank payments can already be fast and inexpensive in many countries. The friction becomes more visible when a company pays a contractor, supplier or subsidiary across currencies and time zones. Correspondent banks, cut-off times, intermediary fees and local holidays can make the final cost or delivery time difficult to predict.
Stablecoins can separate the movement of value from banking hours. A token can be transferred around the clock, and a regulated payment provider can convert it at either end. Circle’s cross-border payment infrastructure, for example, uses USDC for settlement between participating financial institutions while local partners deliver fiat currency to recipients. Stripe has also introduced stablecoin balances and payouts for eligible businesses in a large number of countries.
The benefit is clearest when both sides already have suitable infrastructure. If the recipient immediately converts the funds, the process may reduce settlement time without forcing that business to retain cryptoassets. If either side lacks reliable conversion, compliant custody or support for the correct network, however, the promised efficiency can disappear into fees, manual checks and failed transfers.
Treasury teams care about timing as much as transaction fees
A payment that arrives sooner can improve cash visibility and reduce the amount of money trapped between accounts. That matters to marketplaces paying sellers, employers managing international contractors and companies moving liquidity between entities. Continuous settlement can also reduce dependence on pre-funding accounts in several regions, although the actual benefit depends on the provider’s banking relationships and redemption process.
Faster movement introduces new controls. Finance teams need clear approval limits, wallet governance, reconciliation rules and a policy for converting balances. They also need to know whether reserves are segregated, what happens if an issuer or intermediary fails and which entity is responsible for sanctions screening and transaction monitoring. An irreversible blockchain transfer makes accurate beneficiary data and network selection especially important.
Stablecoin settlement still needs a fiat operating layer
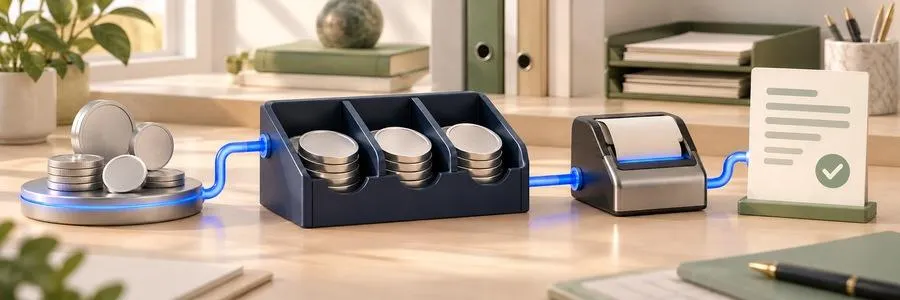
Settlement is only one stage of the payment lifecycle. A stablecoin may move value between institutions quickly, but most companies still need to receive customer payments, hold working capital, convert currencies, pay suppliers and reconcile transactions in conventional money. Payroll, taxes and many local expenses continue to depend on bank based rails and records that fit established finance controls.
A multi currency business account can serve as that operating layer. Fyorin gives businesses access to accounts in more than 100 currencies through one onboarding and a single interface, with local payment routes, approval controls, transaction tracking and connections to accounting systems. The value lies in making ordinary treasury work visible and manageable across currencies, regardless of which compliant rail moves a particular payment.
The two layers can therefore be complementary. Stablecoins may improve the settlement leg for selected cross border flows, while multi currency accounts and local payment routes handle collection, conversion, supplier payment and reconciliation. The useful question for a finance team is not which technology wins, but how each rail fits into a controlled workflow with clear ownership, costs and accounting records.
Regulation is becoming part of the product
Stablecoin growth is occurring alongside uneven regulation. The Bank for International Settlements has noted that properly designed and regulated arrangements could improve some cross-border payments, while also warning about governance, settlement, liquidity and operational risks. Implementation still differs widely between jurisdictions, so a service available to one company may not be available to another with a similar business model in a different country.
The regulatory question is broader than whether a particular token is legal to hold. Businesses may need to consider licensing of intermediaries, reserve disclosure, redemption, consumer or client-money protections, data requirements, sanctions compliance and tax treatment. They should also distinguish between an issuer’s promise and the protections attached to a bank deposit. A stablecoin balance may be designed to maintain parity with a currency without being legally equivalent to cash held at a bank.
The hidden rail may matter more than the visible token
The most durable version of this trend may be the least dramatic. Businesses do not necessarily want to manage seed phrases, choose networks or expose staff to token prices. They want suppliers paid on time, balances visible, fees explained and records ready for audit. Stablecoins become useful when providers turn blockchain settlement into ordinary financial operations with clear responsibilities and reliable support.
That also explains why traditional payment companies are adding stablecoin capabilities instead of being displaced overnight. Card networks can connect token-funded accounts to familiar merchant acceptance. Fintech platforms can combine stablecoin settlement with local bank transfers. Accounting and payables systems can remain the control layer while a different rail moves value underneath.
Stablecoins are not yet the universal infrastructure for global business payments, and their risks should not be minimised. Adoption data, product launches and network investment nevertheless show that they are becoming a real option for selected flows. The change is quiet because much of it happens between institutions. If the model succeeds, the defining feature will not be that every company becomes a crypto company; it will be that international payments become faster while the technical machinery recedes from view.
